
WOW, the market has picked up a lot in the past few weeks. We are seeing multiple offers for the first time in a long time. Inventory in the valley is dropping which should lead to rising prices this year. It is a GREAT TIME to make a purchase before the prices start climbing.
Call me and let's start looking for your dream home!
Ken
951-760-3833
Sunday, April 12, 2015
Monday, April 6, 2015
SPENCER'S CROSSING DREAM HOME! 5 BR, 3 BA; 1 FULL BR AND FULL BATH GROUND FLOOR
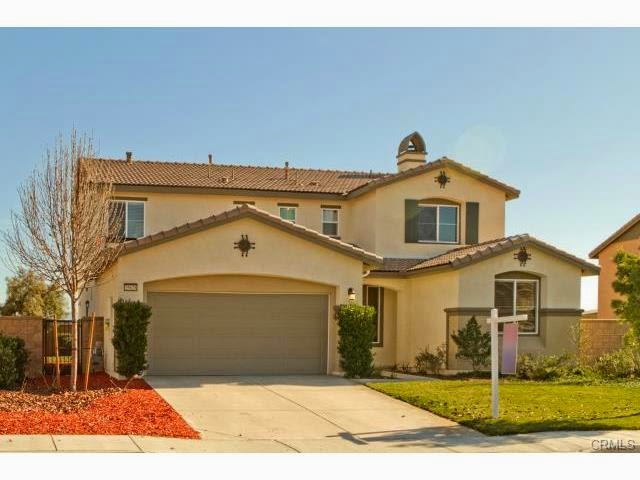
OPEN HOUSE THIS SUNDAY FROM 12 NOON - 4 PM
35628 Hawkeye ST, Murrieta 92563
List Price: $379,000
Orig. List Price: $379,000
Price Per Sqft: $132.83
Property Type: Single Family Residence (D)
Bedrooms: 5
Bath(F,T,H,Q): 3,0,0,0
Sqft (Src): 2,860 (Assessor's Data)
Ac/LotSqft (Src): 0.19/8,276 (A)
Year Built: 2010/Assessor
Stories: Two Level
Sale Type: Standard
Remarks : UPDATE: SELLER OFFERING $5,000 BONUS TO REAL ESTATE AGENT REPRESENTING BUYER. IF YOU ARE A BUYER WHO DEALS DIRECT WITH LISTING AGENT, SELLER WILL CONTRIBUTE THE $5,000 BONUS TO YOU TO HELP WITH YOUR CLOSING COSTS! HOW AWESOME IS THAT?! UPDATE: PRICE JUST REDUCED $20,000 ON 03/13/2015! FROM $399,000 TO $379,000!! SELLER NEEDS TO RELOCATE! Spencer's Crossing Dream Home! 5 Bedrooms, 3 Baths, 3 Car Garage - Full bedroom and full bath downstairs. Huge open island kitchen with custom cabinets. Formal Dining Room, Formal Living Room and Den with Fireplace. Media area/loft on second floor with built in desk. Laundry room upstairs. 20 Solar Panels (monthly lease is only $120.48 per month with average electricity bills under $25 per month!). Large Master Bedroom with walk in closet. Garden tub & Separate Shower with Double Vanities. Dual A/C Units with NEST thermostat that can be controlled from anywhere using your cell phone. Ceiling fans in some rooms. Very large back yard that backs up to the end of a cul-de-sac street for quiet and peaceful backyard solitude. Spencer's Crossing offers spectacular recreation areas to delight the sports enthusiast and the social butterfly. From barbecues to pool parties and team athletics, these special places provide a great backdrop for neighbors to become friends. Here, fun and games are a way of life. 11.5 Acre Sports Park, Lighted Soccer & Baseball Fields, Basketball Court, Tot Lots, Concession Stand, Walking Trails. Four miles of community trails right outside your door will connect you to nature and to neighbors. MURRIETA SCHOOL DISTRICT!!
Directions : From I-15, Winchester Rd West; Left on Max Gillis Blvd; Right on Leon Rd; Right on Pennycress Ln; Right on Hawkeye St.
Contact: Ken Hall at 951-760-3833
www.KenHallProperties.com
www.JustListedInSpencersCrossing.info
***********************


Thursday, March 19, 2015
My Dad's Birthday Today

My Dad's Birthday today, March 19th. Edward Lee Hall would have been 85 today. Passed away in 2013. This pic is from probably 1967. He and my Mom owned an A & W Drive-in Restaurant back in the day. Loved those cool A & W paper hats. I'm the fat kid in the middle, along with my beautiful sis, Lynn.
******************
Saturday, March 14, 2015
Tax Break Rewards Homeowners Who Make Home Energy Improvements
If you installed energy-efficient home improvements in 2014, you may be eligible for a $500 tax credit. Among the home improvements that might qualify for the tax credit:
- Doors
- Windows
- Insulation
- HVAC systems
- Water Heaters
- Roofs
- Skylights
- Biomass stoves
Tax credits are valuable because they offset the tax you owe, dollar for dollar. For example, if you owed $10,000 in taxes, a $500 tax credit would reduce what you owe to $9,500.
The Residential Energy Tax Credit had expired at the end of 2013, but just last week, Congress renewed it through 2014. That means you may be able to claim the tax credit when you file your 2014 federal taxes. Congress did not extend the tax credit through 2015.
Warning: It may take a while for the IRS to update its website with information about the renewal, and to post a 2014 version of Form 5695, which you’ll use to claim the credit.
Check the Energy Star website to see if the specific energy-efficiency home improvements you made qualify for the credit. Give that site a few weeks to get updated with the latest information, as well.
 The Fine Print
In general, you’ll get a 10 percent tax credit for installing energy-efficiency improvements. But, your tax credit is capped for some items. For example, you can’t claim more than $200 for windows, and a new air conditioner will earn you no more than a $300 tax credit.
There’s also a lifetime cap of $500, so if you took the tax credit in prior years, you have to subtract the credit you claimed from $500. For example, if you took $400 in 2013, you can only take the remaining $100 in 2014.
The cost to install your energy-efficiency improvements may, or may not, be included. For example, window installation is included, but insulation installation is not.
This tax credit applies only to your main principal residence.
Call me if I can be of help in any way!
Ken
951-760-3833
kenahall@gmail.com
Tuesday, March 3, 2015
Homeowner Tax Tips for Your Best Return: Deducting Mortgage Interest
The mortgage interest deduction is one of the largest tax benefits homeowners get. Here’s what you need to know to take advantage of it:
If you itemize your deductions on Schedule A of Form 1040, you can include the interest you paid on your home mortgage of up to $1 million ($500,000 for married, filing single) as long as you used the loan to buy, build or improve your home.You can generally deduct the interest on a home equity loan of up to $100,000 ($50,000 for married filing single) used for any purpose, as long as the home equity debt plus your first mortgage don't add up to more than the value of your home.
Get more details about the Mortgage Interest Deduction in Internal Revenue Service Publication 936.

Here are 10 more things you need to know to claim your mortgage interest deduction:
- In general, you have to be legally obligated to pay the mortgage. In other words, you can’t deduct mortgage interest paid, for example, on your parents' home unless you have a legal duty to pay their mortgage.
- If you have a high income, the Alternative Minimum Tax can affect your ability to deduct mortgage interest.
- Your mortgage must be a secured debt, meaning your lender can foreclose on your home if you don’t pay your mortgage.
- Your home can be a boat, mobile home, house trailer, condominium, cooperative or similar property, which has cooking, sleeping and toilet facilities.
- You can deduct late payment charges as though they were interest as long as your lender didn't perform a specific service in exchange for the fee.
- If you pay off your home mortgage early and you have to pay a prepayment penalty, that amount also counts as interest, as long as your lender doesn't charge the fee in exchange for a specific service performed or to cover the cost of something connected to your mortgage (like giving you a payoff statement).
- If you make annual, or periodic, rental payments on a redeemable ground rent, you can generally deduct them as mortgage interest. Payments made to end the ground lease, and payments for nonredeemable ground rent, aren't deductible as mortgage interest.
- Reverse mortgage interest generally isn't deductible until it’s paid – and you don’t usually pay interest on a reverse mortgage until you (or your heirs) sell your home and pay off the reverse loan.
- If you own a cooperative apartment, you’ll get a Form 1098 from the co-op telling you how much interest you paid on any building-wide mortgages. You can deduct that amount along with the interest you paid on your individual unit loan (if you got a mortgage to buy your shares in the co-op).
- The rules change if you got your mortgage on or before Oct. 13, 1987
If I can help you in any way, give me a call, 951-760-3833.
Ken
kenahall@gmail.com
951-760-3833
***************
Monday, February 9, 2015
3 Ways To Protect Your Credit After A Data Hack
When your credit card or bank accounts are compromised by a data breach, like the ones that affected millions of Home Depot and Target consumers, take these three steps to protect yourself:
#1 Watch Out For ScammersAfter a breach, scammers send texts, emails and make calls that seem like they’re coming from the company whose data was breached.
This communication, known as phishing, might include the personal information that was stolen by the hackers.
Don’t be fooled because your bank account, Social Security, or credit card number is mentioned.
If you have questions, reach out to the company that issued the card or your bank representative.
- Don’t respond.
- Don’t give any additional information.
- Delete the emails and texts.
- Hang up on callers.
 #2 Watch Your Accounts
Review your bank and credit card statements as soon as they arrive. Report suspicious activity immediately to protect your rights as a consumer.
The easiest way to keep an eye on your credit is to purchase a credit monitoring service that sends you an alert when your balance changes or a new account is opened in your name.
You can also monitor your credit by asking for a free copy of your credit report three times a year from AnnualCreditReport.com, or by calling (877) 322-8228.
You can pull one credit report a year from each bureau. Since there are three bureaus, you can pull your credit report every four months or so for free.
Some websites, including Credit Karma and Credit Sesame, offer free credit scores and monitoring.
#3 Consider Freezing Your Credit
A credit freeze isn’t going to stop the hackers from using your stolen credit card information to make charges, but it will stop new accounts from being opened in your name.
While your credit is frozen, however, you can’t open new accounts. That’s an issue if you’re in the process of getting a mortgage, applying for a job, renting an apartment or buying insurance.
The Federal Trade Commission has a great article that explains how a credit freeze works.
To freeze your credit, contact the three credit bureaus:
Equifax (800) 525-6285
Experian (888) 397-3742
TransUnion (800) 680-7289
Questions? Call me anytime.
Ken
951-760-3833
kenahall@gmail.com
Monday, February 2, 2015
Put Cash In Your Pocket: Caulk Your Way To Lower Utility Bill
************
Applying caulk and insulation to seal the cracks and openings in your home’s exterior helps keep the air you pay to condition in your home and the outside air out -- and that can lower your utility bill.
 Buy The Right Caulk
Applying caulk and insulation to seal the cracks and openings in your home’s exterior helps keep the air you pay to condition in your home and the outside air out -- and that can lower your utility bill.
Use these tips from the Paint Quality Institute to get the job done right:
Look For Problem Areas
Begin the battle with a walk-around inspection of your home's exterior.
Make a list of cracks, gaps or holes – especially where different surfaces meet, or where pipes and vents penetrate the walls.
Look at your old caulk. Is it cracked or separated from the surrounding surface? These areas are energy sieves and prime spots to caulk or insulate.
If you find old caulk that is damaged or deficient, remove every last bit of it with a scraper or putty knife.
Clean the adjacent surfaces, then sand them smooth. Prime any areas where bare wood shows so the new caulk adheres properly and creates a weather-tight seal.
Buy The Right Caulk
When purchasing replacement caulk, choose a top quality product. The best choices are water-based all-acrylic caulk, or siliconized acrylic caulk. Similarly named “silicone” caulks can’t be painted.
Be systematic when applying the new caulk. Work your way around the exterior of your home, completing each wall or surface area before moving on to the next.
Fill every gap and seam with a generous bead of caulk. Remember, this is your defense against air loss, so you don’t want to skimp.
As soon as you apply the bead of caulk, run a wet finger over the full length of the bead, using a slight amount of pressure. By “tooling” the caulk in this way, you’ll ensure it adheres to the surrounding surface and tightly seals the space.
If some gaps are too large to caulk – typically, those that are more than a quarter-inch wide – fill them instead with a polyurethane foam insulation product.
Unlike caulk, which has a tendency to shrink slightly as it dries, some polyurethane foam products actually expand after being applied, making them ideal for filling large openings and cavities in your home.
Check Your Work
After working your way around your home and filling every gap and opening, take a short break. Then, walk around your home one last time to make sure you didn’t miss anything.
Don’t be surprised if you spot a few areas that still need attention. Put the final touches on your work, then put your tools away and enjoy your savings.
And let me know how much it lowers your power bill!
Ken Hall
951-760-3833
kenahall@gmail.com
*****************************
Subscribe to:
Posts (Atom)